Quick answer: To avoid holiday credit card debt, set a total spending cap now, divide it by the weeks left, and pay for gifts from a dedicated holiday fund instead of plastic. If the charges already happened, list every balance, pay more than the minimum, and consider a 0% balance transfer to stop interest while you burn the balance down.
Key takeaways
- Holiday credit card debt is a math problem: total budget divided by weeks left equals your weekly set-aside.
- Your budget should include more than gifts: travel, food, decor, shipping, cards and parties.
- Minimum payments on a holiday balance can drag it out for years. Pay a fixed amount instead.
- A 0% balance transfer can turn January interest into principal progress, if you read the fine print.
- Open every January statement on purpose, with a plan, not a flinch.
Whether you are a few months out or staring at a January statement, this guide gives you the numbers and the steps. If you want to see lower-rate options along the way, you can request free options to lower your interest rate using the form on this page.
Why Holiday Credit Card Debt Snowballs So Fast
Holiday spending feels small in the moment: $40 here, $75 there, a $120 flight change fee. Then the statement arrives and the total is a shock. The cause is rarely one big purchase. It is dozens of small ones nobody tracked.
Interest makes it worse. At a typical card APR (rates vary widely, and many cards sit well above 20%), a $2,000 holiday balance can cost roughly $35 to $45 a month in interest if you carry it. Make only minimum payments and that balance can linger for years. You can see exactly what that looks like with the credit card minimum payment calculator.
Here is where holiday money usually leaks:
- Gifts: the obvious category, and often only half the total.
- Travel: gas, flights, bags, rental cars and last-minute changes.
- Food and hosting: groceries, party supplies, takeout during busy weeks.
- Extras: decor, wrapping, shipping, cards, teacher and coworker gifts, charity asks.
- Buy now, pay later: pay-in-4 orders that stack up quietly. More on those in the pay-in-4 trap guide.
Step 1: Set Your Holiday Budget Now
The best time to set a holiday budget is as early as possible, ideally in the fall. The second best time is today. Use this simple formula.
- Pick a total cap. Look at last year’s statements and bank activity from November through December. Subtract 20% to 30% as a starting target.
- Divide by weeks left. A $900 budget with 15 weeks to go is $60 a week set aside.
- Split by category. Assign dollar amounts to gifts, travel, food and extras before you shop.
- Fund a separate account. A free savings account labeled “Holidays” keeps the money out of your daily spending.
If $60 a week is out of reach, shrink the plan, not the math. Fewer gifts, a name draw, or homemade presents all beat a January balance. If money is tight year-round, the tight-income burn plan shows how to build realistic margins.
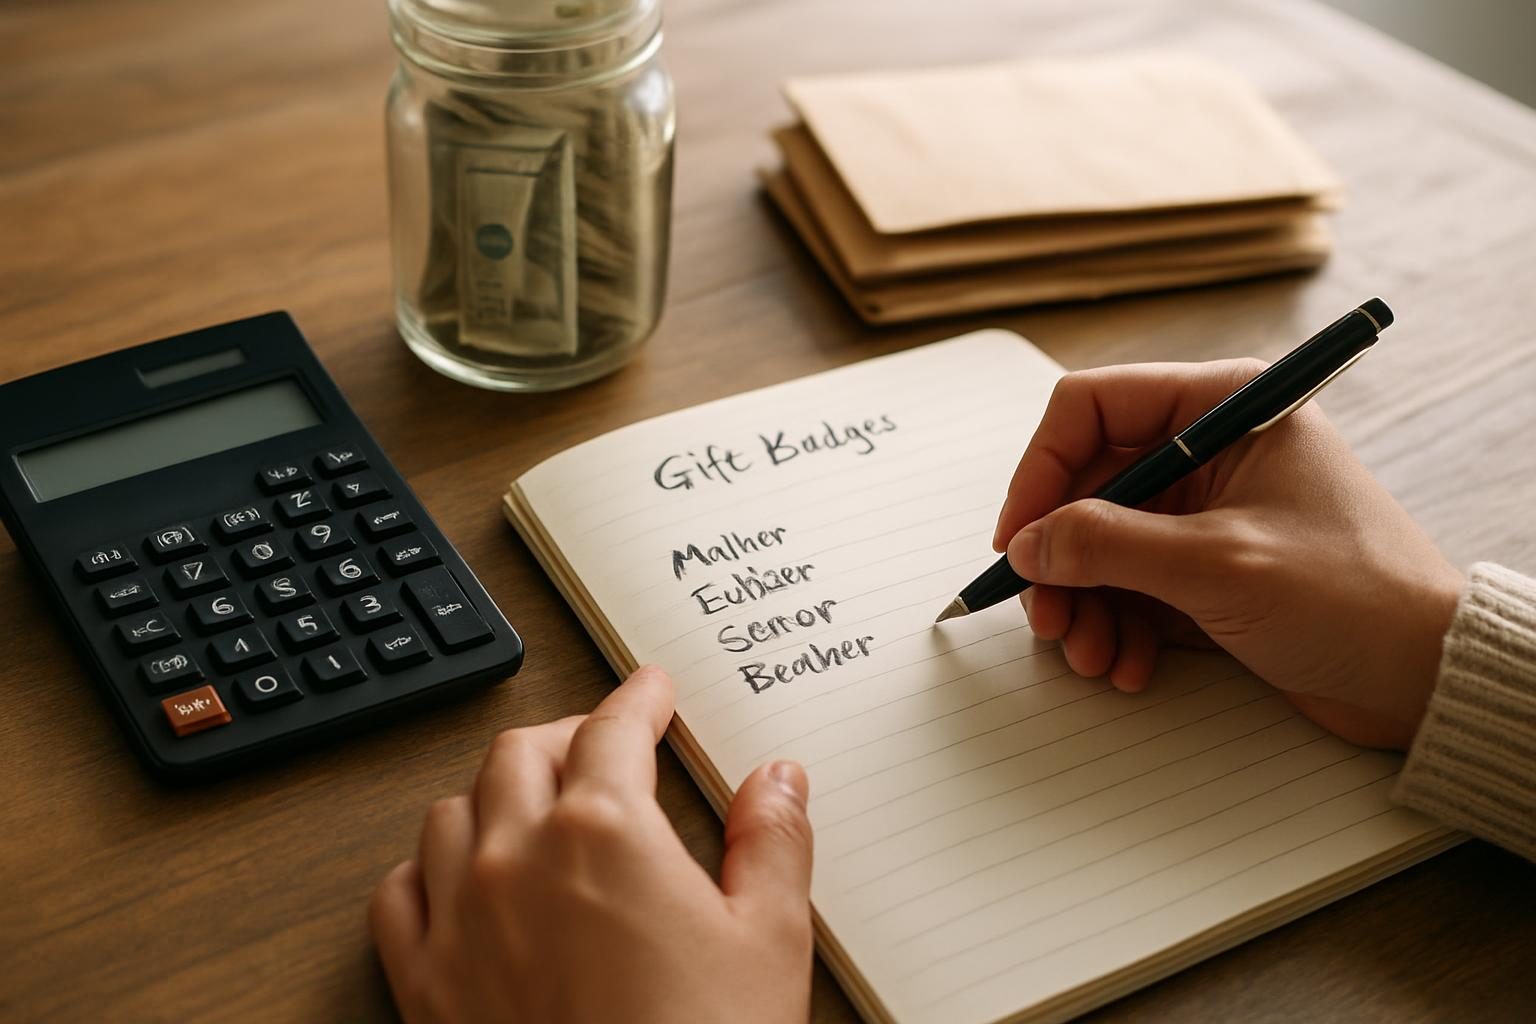
Pro tip: Build the budget list per person. Write each name, a dollar limit and a gift idea. A line item with a name beside it is much harder to blow past than a vague “gifts” bucket.
A holiday budget is just your total spend divided by the weeks you have left to save it.
Step 2: Cut Holiday Costs Without Cutting the Joy
You do not need to cancel the holidays. You need to trim the parts nobody will remember. Try these moves, listed roughly from easiest to biggest impact.
- Run a name draw. Families and friend groups often agree to buy for one person instead of everyone.
- Set a per-gift limit. Even a modest cap, agreed in advance, takes pressure off everyone.
- Shop with a list and a price ceiling. Check prices before sales so you know what a real deal is.
- Give time or experiences. A planned dinner, a babysitting night or a shared hobby can mean more than another gadget.
- Make it potluck. Hosting a meal for 12? Ask each guest to bring a dish.
- Ship smart. Order early to avoid expedited fees, and consolidate shipments where you can.
- Skip the unnecessary. Pass on extras you buy out of habit, like cards for every acquaintance.
You can also run a short spending challenge to free up cash. The 12 money saving challenges include options that fit a fall budget, and the debt payoff challenges hub has more ideas.
Step 3: Use Cards Carefully If You Must
Sometimes a card is the only practical option, especially for online orders and travel. If you use one, use it with guardrails.
- Charge only what your holiday fund can cover within the next statement or two.
- Track every swipe in a note on your phone or a simple spreadsheet.
- Check your card’s grace period. If you pay the full statement balance by the due date, you generally avoid interest on new purchases. Carry a balance and that grace period often disappears.
- Avoid new store cards opened for a one-time discount, which can add another due date and rate to manage.
For a closer look at how interest is applied, our guide to how credit card interest is calculated breaks it down in plain English.
Interest does not care that the charge was a gift. It starts the day your grace period ends.
Holiday Credit Card Debt in January: Your Payoff Plan
If the holidays already happened, here is the sequence that works. Do it in one evening if you can.
- Open every statement. Write down each balance, APR, minimum payment and due date. Include BNPL plans.
- Find your real number. Add up what you owe from the holidays alone, then your total card debt.
- Pick a fixed payment. Choose an amount above the minimums that you can sustain, even if it is $50 more.
- Choose a method. The debt avalanche method attacks the highest APR first and saves the most interest. The snowball, via the debt snowball worksheet, attacks the smallest balance first for quick wins.
- Automate it. Set up automatic payments so the plan runs without willpower.
- Find extra cash. Sell gifts you will not use, pause subscriptions, and put any January windfall toward the balance.
Want your debt-free date in numbers? Plug your balances into the credit card payoff calculator or the Debt Burn-Down Calculator. For the full blueprint, see how to pay off debt fast.
Speed It Up: Balance Transfers and Lower Rates
If your holiday balance sits at a high APR, a 0% introductory balance transfer card can pause interest for a set promotional period. Every dollar you pay then goes to principal.
Run these checks before you apply:
- Transfer fee: commonly in the range of 3% to 5% of the amount moved (an estimate; confirm with the issuer).
- Promo length: divide your balance by the number of promo months to see the monthly payment needed to finish on time.
- Credit limit: your new limit may be smaller than your debt. See what to do when your debt is bigger than the limit.
- After the promo: the regular APR applies to whatever remains.
Test the math with the balance transfer calculator, and review the balance transfer guide and the common balance transfer mistakes before you commit. Approval and terms depend on your credit, and a transfer is not right for everyone.
You can also ask your current issuer for a lower rate. Our upcoming piece on how to negotiate a lower credit card interest rate will walk through what to say.
Ready to compare options? Request free options to lower your interest rate using the form below. It is no-obligation.
FAQ
How much should I spend on the holidays?
There is no universal number. A practical rule is to spend only what you can pay in cash, or what your holiday fund covers, by the first statement after the season. Start from last year’s actual spending and trim it by 20% to 30%.
Is it better to pay off holiday debt with the avalanche or snowball method?
The avalanche saves more in interest because it targets the highest APR first. The snowball builds momentum by clearing the smallest balance first. The best method is the one you will stick with. Both work if you pay consistently.
Will a balance transfer hurt my credit?
A new card typically triggers a hard inquiry, which can cause a small, temporary dip. Over time, lower utilization from paying down debt can help your score. See how a balance transfer affects your credit score for details.
What if I cannot pay more than the minimum?
Start by finding even small savings, such as pausing a subscription, then pay the minimums on time to avoid late fees and protect your credit. A lower rate through a transfer or refinance can make the same payment go further. For tailored guidance, a nonprofit credit counselor or financial professional can review your full situation.
See free ways to lower your holiday credit card interest
A partner will review your options with you, free and with no obligation, so you can start burning down your balance.

