Quick answer: The debt payoff milestones worth celebrating are the ones that prove your system is working: your first extra payment, your first paid-off account, every 10% of total debt cleared, and the day your balance drops below what you started with by half. Mark each one with something free, like a tracker update, a walk, or a note to your future self, so the celebration never adds to the balance you are burning down.
Key takeaways
- Milestones keep you going during the long middle stretch, where most people quit.
- Use both percentage milestones (10%, 25%, 50%) and behavior milestones (first extra payment, first month under budget).
- Celebrate for free. A $200 dinner can wipe out weeks of progress.
- Write your milestones down before you start so you know exactly when to celebrate.
Paying off debt is a math problem, but you are the one who has to stick with it for months or years. Milestones turn a long, quiet grind into a series of wins you can see and feel. This list gives you 15 of them, grouped by stage, with a free way to mark each one.
If you do not have a plan yet, request free options to lower your interest rate using the form on this page, then come back and pick your first milestone.
Why Debt Payoff Milestones Matter
A balance that shrinks by $400 a month feels invisible when you owe $25,000. Milestones break that big number into small finish lines, so you get a win much sooner than “debt-free.”
- They fight burnout. The middle of a payoff plan is the hardest part. A checkpoint every few months gives you something to aim at.
- They make progress measurable. You can see the gap closing instead of guessing.
- They reinforce habits. Celebrating the behavior (not just the balance) keeps you doing the thing that works.
If you are still choosing a method, our debt snowball vs. avalanche comparison will help you decide which order your milestones should follow. The snowball tends to deliver early wins faster because it clears small balances first.
Starter Milestones: Proof You Have Begun
These cost nothing and happen in your first few weeks. They matter because starting is the hardest step.
- You listed every debt. Balance, rate, minimum payment, due date. Many people have never seen the full picture. Celebrate by saving the list somewhere you will see it.
- You know your debt-free date. Plug your numbers into the Debt Burn-Down Calculator and write the projected month on your wall or fridge.
- You made your first extra payment. Even $25 above the minimum counts. It proves the system works.
- You completed one full month on plan. No missed payments, no new charges on the cards you are paying down.
Pro tip: Take a screenshot of your starting balances. Looking back at it a year later is one of the best free rewards in the whole process.
Need help building the plan itself? How to make a debt payoff plan in one evening walks you through it step by step.
The best celebration is one that costs nothing and reminds you why you started.
Percentage Debt Payoff Milestones to Track
Percentage milestones work because they scale to any debt size. Pick the ones that fit your total, and track them on a chart.
- 10% paid off. Example: $2,500 cleared on a $25,000 total. The first 10% is often the most emotional.
- 25% paid off. A quarter of the way. Interest is usually starting to take a smaller bite.
- 50% paid off. The halfway mark. Mathematically it is usually past the hardest stretch, since interest charges shrink as principal falls.
- 75% paid off. The home stretch. Your payments are doing more principal work than ever.
- 90% paid off. Close enough to taste it. Consider a final push with a windfall.
Visual trackers make these moments feel real. Try one of our free debt payoff tracker printables or a debt-free chart to color in each step.
Account-Level Milestones: Closing Out Balances
Every account you zero out is a real, permanent win. These are the milestones that free up cash flow.
- Your first account hits $0. If you use the snowball, this is likely a small card or store balance. Roll its old payment into the next debt right away.
- Your first card is under 30% utilization. Many credit scoring models look at the share of your limit you are using, so this is a meaningful marker. Keep in mind that score effects vary.
- You clear a high-rate balance. If you are using the avalanche, paying off your highest-APR debt is the biggest dollar win even if the balance is large.
- You beat a deferred-interest deadline. Paying off a store card before promotional interest kicks in is worth marking. See our guide to store credit card payoff for how that deadline works.
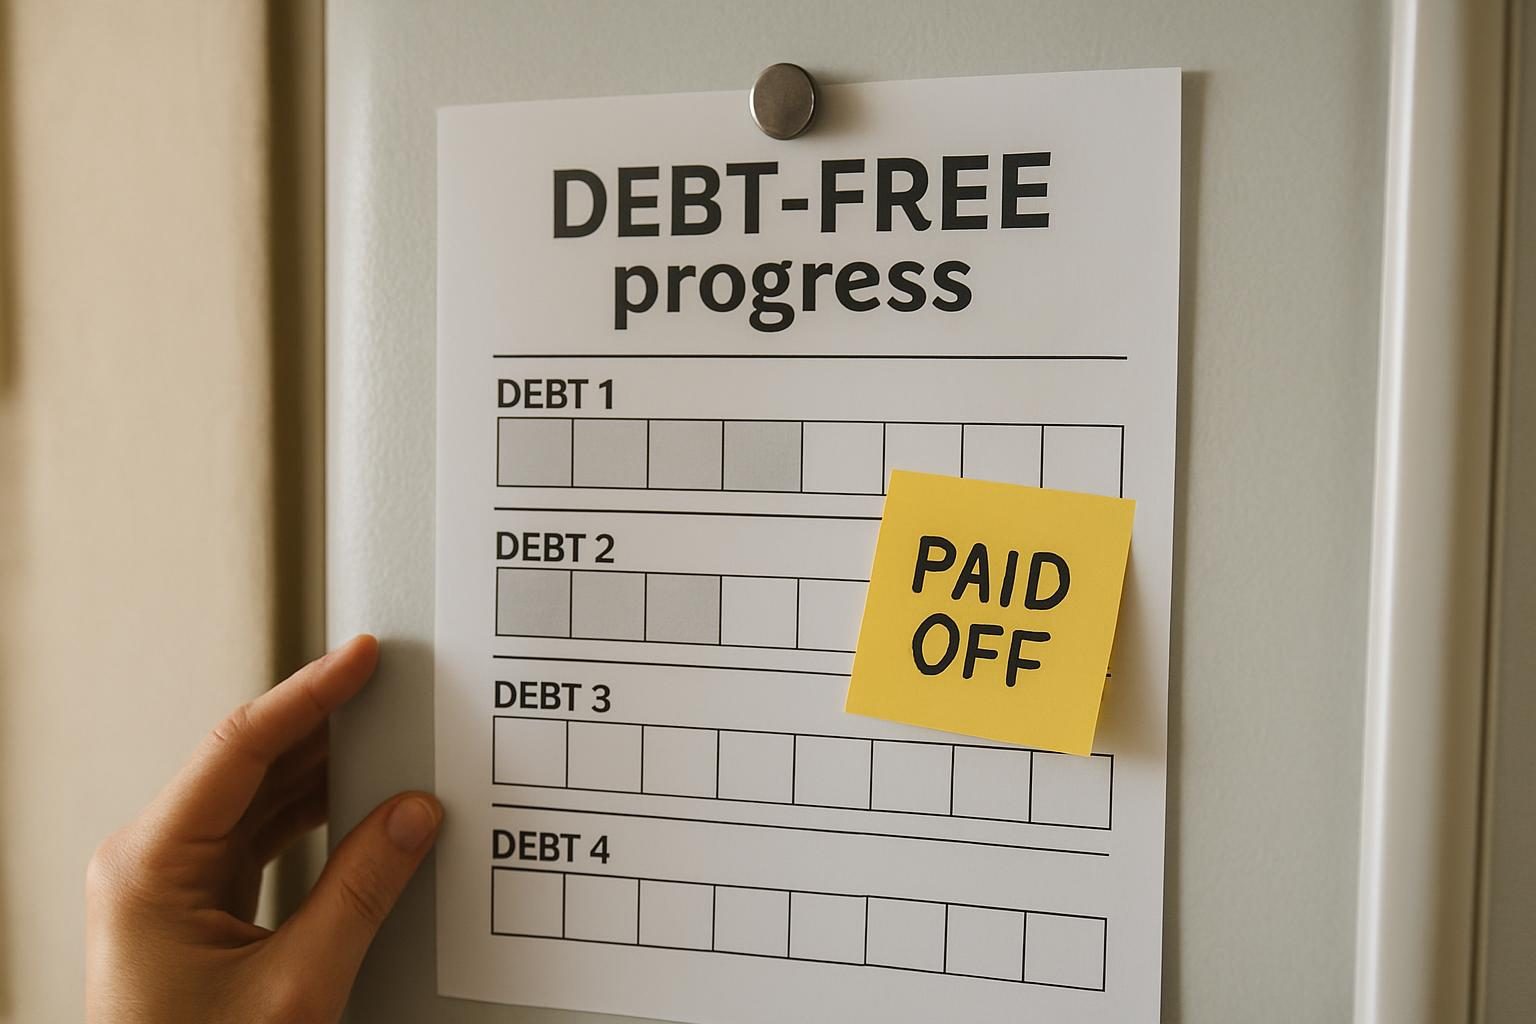
Each paid-off account also gives you a free way to celebrate: cross it off the list, tear up a printed statement, or add a big check mark to your tracker.
Every paid-off account frees up a payment you can throw at the next one.
Big-Picture Milestones: The Ones You’ll Remember
These are the later-stage wins that change how your finances feel day to day.
- You pay off all credit cards. Revolving debt tends to be the most expensive, so this often cuts your interest costs sharply.
- You finish a loan early. Use an early payoff calculator to see how many months and dollars you saved, and write that number down.
- You pay off your car. No more payment, and you own the title. Our car loan payoff guide covers how to get there sooner.
- Your student loans drop below a set number. Pick a round figure like $10,000 or $5,000. The student loan payoff guide can help you plan the push.
- You hit a mortgage equity milestone. Reaching 20% equity is a common one, since it can matter for ending private mortgage insurance on some loans. Check your lender’s rules, and see the mortgage payoff guide for early payoff ideas.
- You are debt-free except your mortgage. A huge shift in monthly breathing room.
- Your final payment. The big one. Take a photo of the $0 balance.
Free Ways to Celebrate Each Milestone
The whole point is to feel the win without undoing it. Here are ideas that cost nothing.
- Update your tracker. Color it in, add a sticker, or move the thermometer line.
- Write a short note to yourself. What you did, how it felt, what you will do next.
- Share it with someone you trust. A partner, friend, or an online community. Couples can find tips in paying off debt as a couple.
- Take a free outing. A hike, a library visit, a picnic, a sunset walk, a free local event.
- Cook something special from the pantry. It pairs well with a no-spend or money challenge.
- Do a “nothing” day. Movies you already own, a long bath, a phone-off evening.
If you want a structured way to keep momentum between milestones, the 52-week money challenge chart is a simple free option. And for deeper next steps, a debt-free countdown can keep the finish line in view.
Speed Up Your Next Milestone
Math helps here. If a lower rate puts more of each payment toward principal, every milestone arrives sooner.
- 0% balance transfer cards can pause interest on card debt for a promotional period, usually with a transfer fee (often estimated at 3% to 5%). Our balance transfer fee calculator shows if the fee is worth it.
- Consolidation loans can swap several high-rate balances for one fixed payment. See whether it actually helps you pay off cards.
- Refinancing student, auto or mortgage loans may lower your rate, depending on your credit and the market.
Rates and approval depend on your credit and finances, so nothing here is guaranteed. If you want to see what is available, request free, no-obligation options to lower your interest rate using the form on this page. You can also browse our lower your rate page.
FAQ
How often should I celebrate debt payoff milestones?
Aim for something every month or two. Tie small celebrations to behaviors (like a month on plan) and bigger ones to balances (like each 10% or each closed account). Frequent checkpoints keep motivation up.
Is it okay to reward myself with money?
You can, but keep it small and planned. A common approach is to set aside a tiny, fixed amount in advance, so the reward is part of the budget instead of a slip. Free rewards are safer if your budget is tight.
What counts as a debt payoff milestone?
Anything that shows measurable progress: a percentage of total debt paid, a closed account, a lower utilization rate, a first extra payment, or a loan finished early. Choose milestones that mean something to you.
Should I track milestones on paper or in an app?
Either works. Paper is satisfying and visible; apps and spreadsheets are easier to update. Our comparison of debt payoff apps vs. a simple spreadsheet can help you pick.
See free options to lower your interest rate
Partners will share free, no-obligation options so you can hit your next payoff milestone sooner.


