Quick answer: To pay off debt fast, list every balance with its rate and minimum, pick a payoff order (snowball or avalanche), find extra cash in your budget, automate your payments, and funnel every spare dollar to one target debt at a time. Then track progress monthly so each paid-off account rolls its payment into the next one.
Key takeaways
- Speed comes from two levers: more dollars going to debt and a lower interest rate.
- Avalanche (highest rate first) saves the most interest; snowball (smallest balance first) builds momentum. Either beats having no plan.
- Your “gap” is income minus spending. Even a modest gap, rolled forward, compounds fast.
- Automate minimums and the extra payment so willpower is never part of the plan.
- Lowering your rate with a 0% balance transfer or a consolidation loan can shorten the timeline, but only if you stop adding new debt.
Paying off debt is arithmetic before it is anything else. Every dollar of interest you avoid is a dollar that goes to principal, and principal is what you are trying to burn down. This guide walks through the full Burn-Down Plan in six steps, with a worked example you can copy.
Want to see your own numbers as you read? Run them through the Debt Burn-Down Calculator, and if you’d like to explore lower-rate options, you can request free options to lower your interest rate using the form on this page.
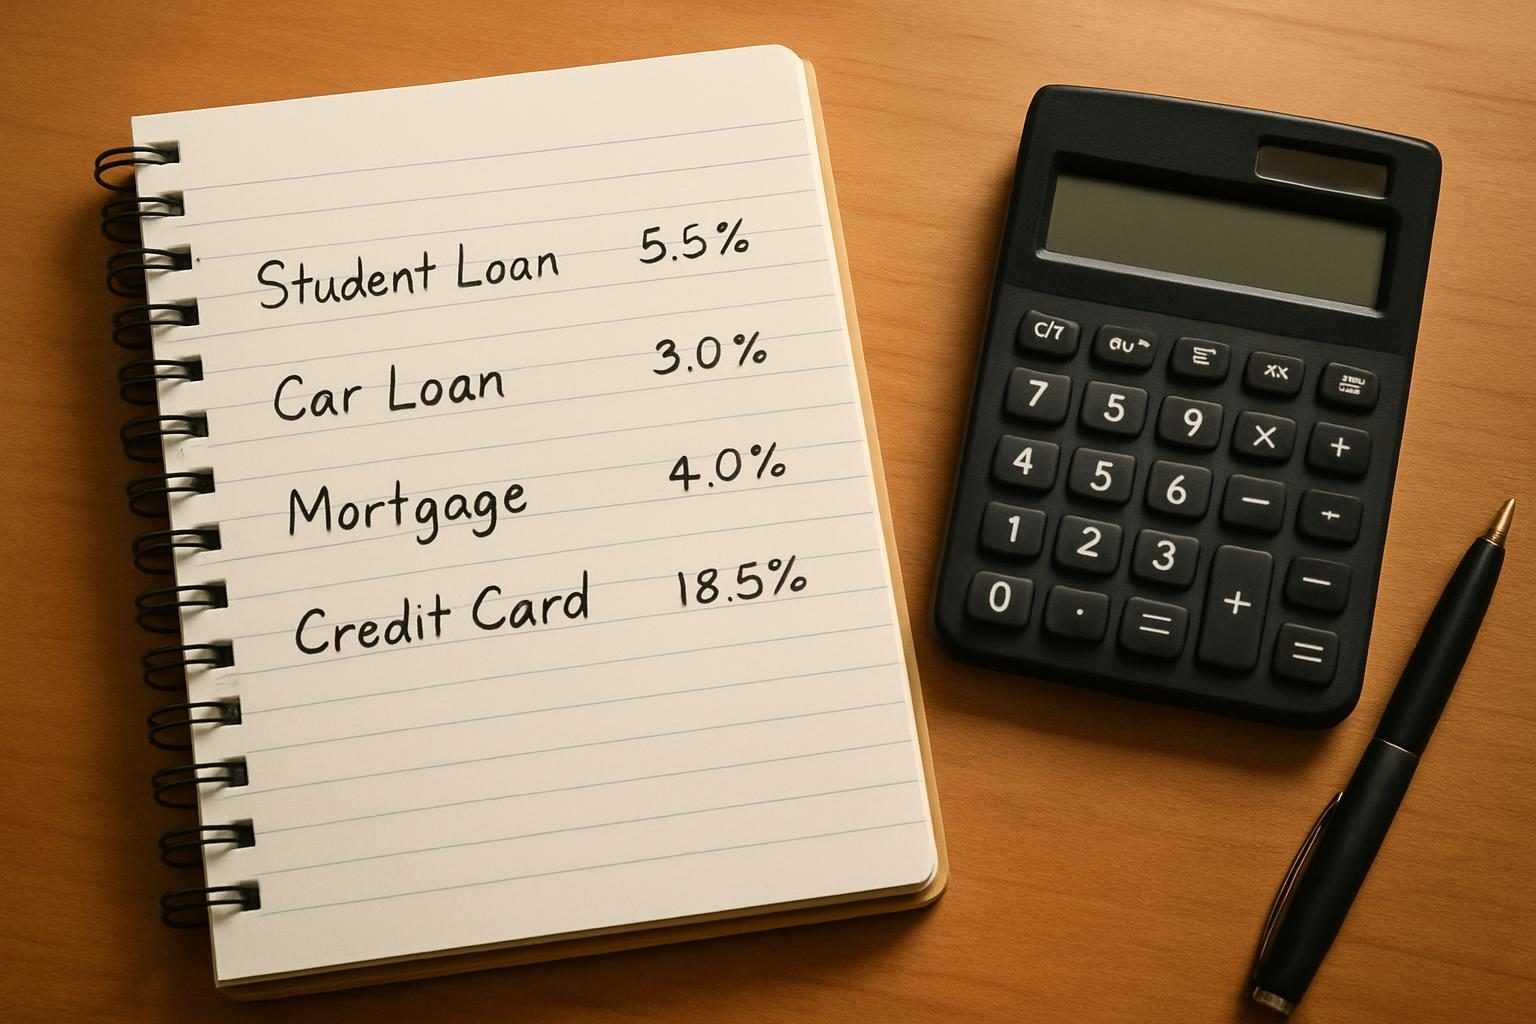
Step 1: List every debt (the full picture)
You cannot beat a number you have not looked at. Pull up every account and write down four things for each one.
- Balance: what you owe today.
- APR: the interest rate (check your statement or online account).
- Minimum payment: the least you must pay each month.
- Due date: so nothing slips.
Include credit cards, personal loans, student loans, car loans, medical bills on payment plans, and buy-now-pay-later balances. Mortgages count too, though they usually come last in the attack order. If BNPL is part of your picture, our BNPL and other debt guide covers the stragglers people forget.
Pro tip: Add up the minimums and the total interest you pay per month (balance × APR ÷ 12). Seeing a number like “$310 a month goes to interest” is a powerful motivator.
Step 2: Pick your payoff method
The two classic methods differ only in the order you attack debts. Both pay minimums on everything and send all extra money to one target.
- Debt avalanche: target the highest APR first. This minimizes total interest and usually gets you debt-free sooner by the math.
- Debt snowball: target the smallest balance first. You knock out accounts quickly, which builds momentum and frees up minimums sooner.
Which should you choose? If you are motivated by numbers, pick the avalanche. If you have struggled to stick with plans before, the snowball’s quick wins can keep you going. The best method is the one you will finish. For a deeper side-by-side, see our debt payoff plans guide, and for the details of the highest-rate-first approach, read about the debt avalanche method.
The best payoff method is the one you will actually stick with until the last balance hits zero.
Step 3: Find the gap (where the extra money comes from)
Your gap is the money you can redirect to debt beyond minimums. There are only three ways to create it, and the strongest plans use all three.
- Trim spending. Review the last two or three months of statements. Subscriptions, delivery fees and unused memberships are common leaks.
- Raise income. Overtime, a short-term side gig, selling unused items, or a tax refund can all be one-time or recurring boosts.
- Lower your interest. A lower rate means more of each payment hits principal. This is where a 0% balance transfer card or a consolidation loan can help.
Short-term spending resets can jump-start this step. Our debt payoff challenges (no-spend months, savings sprints) give you a structured way to free up cash for 30 days at a time.
A worked example: a 3-debt household
Here is an illustrative example. These numbers are made up for demonstration, not a prediction of your results.
- Credit card: $4,000 at 24% APR, $120 minimum
- Car loan: $9,000 at 7% APR, $280 minimum
- Personal loan: $2,500 at 12% APR, $95 minimum
Total minimums: $495 a month. Suppose this household finds a $250 monthly gap, so they put $745 a month toward debt.
Avalanche order: credit card (24%) first, then personal loan (12%), then car loan (7%). The extra $250 goes on top of the card’s $120 minimum, so the card gets $370 a month while the other two get minimums. When the card is gone, its full $370 rolls to the personal loan, then the combined amount rolls to the car loan.
Snowball order: personal loan ($2,500) first, then credit card, then car loan. You see the first account vanish sooner, but you pay more total interest because the 24% card lingers longer.
The key insight in both cases is the roll-forward: when a debt dies, its payment does not go back into your spending. It moves to the next target. That is how a $495 minimum stack turns into a $745 attack.
Plug your own balances into the Debt Burn-Down Calculator to see your projected payoff date under each method. To get a quick estimate in the meantime, you can read up on how long it will take to pay off your debt.
When a debt dies, its payment should never return to your spending; it rolls to the next target.
Step 4: Automate so the plan runs itself
Motivation fades. Automation does not. Set it up once and let the system do the work.
- Autopay every minimum so you never incur late fees or credit damage.
- Schedule the extra payment to your target debt right after payday, before you can spend it.
- Line up due dates with your pay schedule. Many lenders will let you change a due date on request.
- Keep a small starter buffer (even $500 to $1,000, your call) so a surprise expense does not land on a credit card.
Step 5: Attack with a lower rate and a focused target
With the plan set, put every extra dollar on one target. Lowering your rate can accelerate the timeline, so it is worth checking your options.
- 0% balance transfer: moves high-rate card debt to a promotional 0% period, often with a transfer fee (commonly in the range of 3% to 5%, an estimate). It works best if you can pay the balance down within the promo window.
- Consolidation loan: replaces several balances with one fixed payment, often at a lower rate if your credit qualifies.
- Refinancing: student, auto and mortgage refinancing can reduce your rate or payment, but check the fees, the new term and whether you lose any borrower protections.
For specific loan types, see our guides to paying off student loans, paying off car loans early and mortgage payoff strategies. A rate that looks lower can still cost more if it stretches the term, so compare total interest, not just the monthly payment.
Curious what you might qualify for? You can request free, no-obligation options to lower your rate from partners using the form on this page, or browse the lower your rate options page.
Step 6: Track progress and keep the fire lit
What gets measured gets paid. Once a month, update your balances and watch the total fall.
- Update a tracker: a spreadsheet or a printable debt payoff tracker works fine.
- Celebrate each payoff with something free or cheap, then immediately roll the payment forward.
- Re-run the numbers every few months or after any windfall.
- Watch for relapse: new charges on paid-off cards undo the math fast.
Ready to see what a lower rate could do to your timeline? Request your free rate-lowering options with the form below, then plug the new numbers into the calculator.
Frequently asked questions
What is the fastest way to pay off debt?
Increase the dollars going to debt and reduce the interest you pay. Practically, that means finding extra cash, paying one target debt aggressively, and lowering rates where you can. The avalanche method is usually the fastest by the math.
Should I use the snowball or the avalanche?
Avalanche saves more interest; snowball delivers earlier wins. If the interest difference between them is small for your balances, choose whichever keeps you motivated.
Is a balance transfer a good idea?
It can be, if you qualify for a 0% offer, understand the transfer fee, and can pay the balance off before the promo ends. It does not help if you keep charging the old card.
Do I need to talk to a professional?
This guide is educational, not personalized financial advice. If you are behind on payments or facing collections, a nonprofit credit counselor or qualified financial professional can review your specific situation.
See free options to lower your interest rate
A partner will review your situation and share free, no-obligation options like balance transfers or consolidation loans.

